Midwest hail damage · John Beal Roofing since 1947
ACV vs RCV On A Hail Damage Roof Claim
Two policies can cover the same storm and pay very different amounts. The difference is depreciation, and where your policy puts it decides what you pay out of pocket.
Short answer
Actual cash value pays what your roof was worth the moment before the hail hit, meaning replacement cost minus depreciation for age and wear. Replacement cost pays what it costs to put a new roof on today. Most replacement cost policies pay in two parts: an actual cash value check first, then the withheld depreciation released after the work is finished and invoiced. With an actual cash value policy there is no second check, so on an older roof the gap between the settlement and the real cost of the job can be thousands of dollars. Your declarations page names which one you have.
The two numbers on every settlement sheet
Open the loss statement and find the replacement cost value, the depreciation line, and the actual cash value. Replacement cost is the full scope priced at current material and labor. Depreciation is a deduction for how much service life the roof had already used. Actual cash value is the first minus the second, and then your deductible comes off that. On a replacement cost policy the depreciation is usually recoverable, which means it is held back rather than taken away.
That word recoverable is the whole game. Held-back money comes to you after the roof is installed and the final invoice goes in. Money deducted under an actual cash value policy does not come back at all.
How depreciation gets calculated on a roof
Carriers assume a service life for the roof covering and prorate against age. A thirty-year architectural shingle at year twelve carries roughly forty percent depreciation on the covering, give or take, depending on the carrier's schedule and the condition noted by the adjuster. Some line items depreciate and some do not. Labor is sometimes depreciated and sometimes not, and that single choice can move the first check by a wide margin on the same claim.
Ask which schedule was applied and whether labor was depreciated. It is a fair question and the answer is in the estimate file.
Recoverable versus non-recoverable, in real money
Say a roof scopes at twenty-two thousand dollars replacement cost, depreciation lands at seven thousand, and the deductible is two thousand. Under a replacement cost policy the first check is thirteen thousand, and once the work is done and invoiced the carrier releases the seven thousand, so you pay your two thousand deductible and nothing more. Under an actual cash value policy you receive thirteen thousand and the remaining nine thousand is yours to cover. Same storm, same roof, same scope.
This is the number that surprises people, and it surprises them at the worst possible time, which is after the contract is signed.
Why some Midwest roofs are on actual cash value without the owner knowing
Carriers across the Plains and the upper Midwest have been moving older roofs onto actual cash value settlement by endorsement, sometimes at renewal, sometimes when a roof passes fifteen or twenty years. It shows up as a roof surfacing endorsement or a similar schedule attached to the policy. The premium usually drops a little and most homeowners never read the endorsement.
Check now, not after a storm. Find the endorsement list on your declarations page and look for anything referencing roof surfacing, windstorm or hail settlement. If it is there, you are budgeting differently for your next roof than you thought.
Percentage deductibles change the arithmetic again
Many Plains-state policies carry a percentage wind and hail deductible rather than a flat dollar amount. One or two percent of the dwelling coverage, not of the claim. On a four hundred thousand dollar dwelling limit, a two percent hail deductible is eight thousand dollars before the carrier pays anything. Homeowners who remember a one thousand dollar deductible from a water loss are reading the wrong line.
Percentage deductibles are also why a smaller hail claim on a large house sometimes should not be filed at all. If the scope is nine thousand and the deductible is eight, the claim is not worth the file it creates.
Reading the loss statement line by line
Go through the scope the way you would read a parts list. Tear-off and disposal, underlayment, ice and water shield where code requires it, starter, field shingles, ridge cap, pipe boots, vents, drip edge, flashing, and any steep or two-story charges the roof actually calls for. Then check the trade items outside the roof: gutters, downspouts, screens, wraps, paint on dented metal. A short scope is not a denial. It is an estimate written from one visit, and it gets corrected with documentation.
Compare it against your contractor's line-item estimate rather than against a total. Totals hide everything.
What an honest contractor tells you here
If you are on actual cash value with a deep depreciation hit, the right conversation is about scope and financing, not about finding a way to make the carrier pay more than the policy says. We would rather build you a roof you can pay for than sell you a job that leaves a balance you did not plan on. And we will not discount the job to make your deductible disappear. Waiving a deductible is fraud in most Midwest states and it puts the homeowner on the wrong side of it too.
Where the money sits
First check
Actual cash value less the deductible. Arrives soon after the estimate is approved and is usually made out to you and your mortgage company.
Second check
Recoverable depreciation, released after the roof is completed and the final invoice is submitted. Only exists on replacement cost policies.
Your share
The deductible, plus any upgrade you choose above the approved scope, plus non-recoverable depreciation if your policy is actual cash value.
What we do with the first check
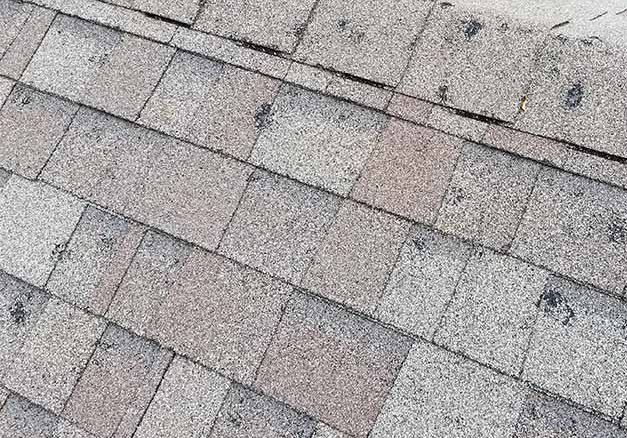
We build to the approved scope, document the completed work with photographs, and submit a final invoice that matches the estimate line for line so the depreciation release is a formality rather than an argument. If items were missed, they go in as a supplement with photographs attached before the final bill. Family-run since 1947, and the paperwork side of a hail job is most of why homeowners call us back.
Depreciation questions we get every week
How do I tell which type of policy I have?
Can I switch from actual cash value to replacement cost?
Do I have to do the work to collect the depreciation?
What is a percentage hail deductible?
Does the carrier pay for code-required upgrades?
Related reading
Free Hail Damage Inspection
No cost, no obligation, and you get the photographs either way.
Free inspection, documented for your claim.
One number reaches dispatch for all forty Midwest metros, answered live 24 hours a day.